
How to use this list
This list is for master's and doctoral researchers in business and management who are interested in corporate social responsibility (CSR) and business ethics. The 2019 version of this page discussed the two concepts but did not offer topics.
Treat each row as a starting point. Check the data you can access, run a search of the last three years, and refine the question with your supervisor. Related pages: business dissertation topics, corporate digital responsibility topics and how to find a research gap.
Business ethics, CSR and sustainability: getting the concepts right
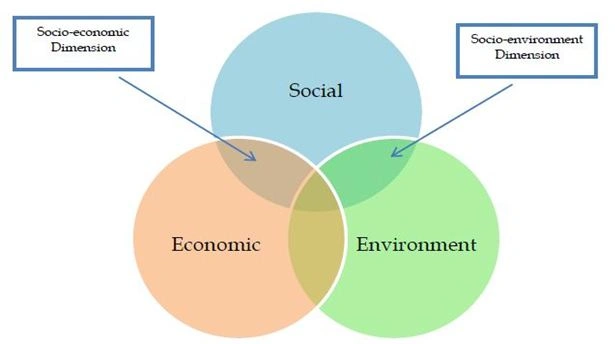
Business ethics studies how people and organisations should act, and how they do act, when decisions involve right and wrong: honesty in reporting, fairness to employees, conflicts of interest. CSR asks what responsibilities a firm has to society beyond its legal obligations, and how it meets them. Corporate sustainability is a third, related concept: Bansal and Song (2017) show that it grew from a different intellectual tradition, focused on the firm's relationship with environmental and social systems, and argue that the two should not be used interchangeably.
The difference between saying and doing runs through the field. Enron promoted its corporate responsibility credentials before it collapsed in 2001 amid accounting fraud, a reminder that CSR communication is not evidence of ethical conduct. Many of the strongest topics below test that gap.
Theme 1: Stakeholders and the business case for CSR
Whether CSR pays is the field's oldest question. A large synthesis of empirical studies found that most reported a non-negative relationship between ESG criteria and corporate financial performance (Friede et al., 2015), but a review of research in corporate finance shows how hard it is to separate cause from correlation, since profitable firms can afford more CSR (Gillan et al., 2021). Topics that identify mechanisms, through employees, customers or investors, are more valuable than another correlation.
| Topic | Possible research question | Likely design and data | Why it matters now |
|---|---|---|---|
| CSR and employee retention | Do employees who perceive their employer's CSR as genuine have lower intention to leave, and is the effect mediated by organisational identification? | Multi-wave employee survey; structural equation modelling | Tests a mechanism rather than a firm-level correlation |
| Consumer response to CSR claims | Does a specific, verifiable CSR claim increase purchase intention more than a vague one? | Online experiment with vignettes; manipulation checks | Separates the effect of CSR from that of communication |
| Stakeholder priorities in family firms | How do owners of family firms decide which stakeholders' claims to prioritise? | Qualitative interviews with owners and managers; thematic analysis | Family firms are under-represented in CSR research |
| The green consumption gap | Why do consumers who state strong environmental attitudes not buy the greener option? | Mixed methods: survey plus purchase data or field experiment | The attitude-behaviour gap is well documented but poorly explained (ElHaffar et al., 2020) |
Theme 2: Ethical leadership and governance
A natural next step is research on how organisations ensure ethical conduct. Ethical leadership is one well-developed route: it describes leaders who act with integrity and promote ethical conduct through communication, reinforcement and decision making (Brown & Treviño, 2006). New governance questions arise with artificial intelligence, where firms are experimenting with ethics-based audits of their systems (Laine et al., 2024).
| Topic | Possible research question | Likely design and data | Why it matters now |
|---|---|---|---|
| Ethical leadership and speaking up | Does ethical leadership increase employees' willingness to report misconduct, and does psychological safety explain the link? | Multi-level survey of teams and leaders | Misconduct is often known internally before it becomes public |
| Codes of conduct in practice | How do frontline managers interpret their company's code of conduct when targets and ethics conflict? | Case study with interviews and document analysis | Codes are universal; evidence on their use is thin |
| Board oversight of ethics | Are firms with board-level ethics or sustainability committees less likely to face regulatory sanctions? | Archival panel data; matching on firm characteristics | Tests whether governance structures change outcomes |
| AI ethics auditing | What do companies examine, and omit, when they audit AI systems against ethical principles? | Document analysis of published audit reports; interviews with auditors | AI governance is moving from principles to practice |
Theme 3: ESG measurement and disclosure
ESG data have become central to CSR research and to investment, and their weaknesses have become clearer. Ratings from different providers disagree substantially, mainly because they measure different attributes and measure them differently (Berg et al., 2022). Research in accounting and finance has also examined whether ESG disclosure and performance affect firm value (Brooks & Oikonomou, 2018). Any thesis using ESG scores must justify its choice of rating and test whether results hold with another.
| Topic | Possible research question | Likely design and data | Why it matters now |
|---|---|---|---|
| Rating divergence and results | Do published findings on ESG and cost of capital hold when a different provider's rating is used? | Replication with two or more rating datasets | Rating disagreement threatens the reliability of the field |
| Mandatory disclosure | Did the introduction of mandatory sustainability reporting in one jurisdiction change the quality or quantity of disclosure? | Difference-in-differences with a comparison group of unaffected firms | Reporting rules are expanding in several regions |
| Readability of sustainability reports | Are firms with weaker environmental performance more likely to publish less readable or more promotional reports? | Text analysis of reports linked to emissions data | Tests whether communication obscures performance |
Theme 4: Greenwashing and the credibility of sustainability claims
Greenwashing, presenting a firm as more environmentally responsible than it is, links business ethics to sustainability. Carbon offsets are a sharp current example: a study of major companies' offset purchases found substantial demand for low-quality offsets, undermining the climate integrity of the voluntary market (Trencher et al., 2024), and a recent review asks whether offsets can be fixed at all (Romm et al., 2025). A review of corporate sustainability research also identifies directions for future work that thesis writers can use to position a topic (Burbano et al., 2024).
| Topic | Possible research question | Likely design and data | Why it matters now |
|---|---|---|---|
| Offset quality and net-zero claims | Are firms with ambitious net-zero claims more likely to rely on low-quality offsets? | Archival study linking corporate climate pledges to offset retirement registries | Offset quality is under scrutiny from regulators and investors |
| Detecting greenwashing | Can the gap between environmental claims in reports and measured emissions be used to identify greenwashing? | Text analysis plus emissions data; validation against known cases | Regulators need practical detection methods |
| Consumer scepticism | Does exposure to a greenwashing scandal reduce trust in green claims by other firms in the same sector? | Online experiment or event study of brand perception | Tests spillovers that harm genuine actors |
Worked example (illustrative)
A master's student begins with "CSR and firm performance". The supervisor points out that the question has been studied many times and that the causal direction is unclear (Gillan et al., 2021). The student narrows to the Theme 3 rating question: do the results of a well-known ESG and cost-of-capital study hold with a different rating provider? The design is a replication with two datasets the university library already licenses, the contribution is clear, and the project fits a one-year timetable.
How to test a topic before you commit
Use the FINER test: is the question feasible, interesting, novel, ethical and relevant (Hulley et al., 2013)? For CSR topics, feasibility usually depends on data. Archival projects need access to ESG ratings, emissions data or disclosure archives, which can be expensive; check what your library licenses. Survey and interview projects need access to employees or managers, and questions about ethics invite socially desirable answers, so plan anonymity and indirect measures. Experimental projects need ethics approval for any deception in vignettes.
Common mistakes
- Using CSR, sustainability and business ethics as synonyms.
- Treating one ESG rating as the truth without testing another.
- Claiming that CSR causes performance from a cross-sectional correlation.
- Relying on company reports as evidence of what a firm actually does.
- Choosing a topic before checking that the data can be obtained.
- Citing blogs and news articles where peer-reviewed evidence exists.
Key takeaways
- Business ethics, CSR and corporate sustainability overlap but are distinct concepts (Bansal & Song, 2017).
- Most studies find a non-negative link between ESG and financial performance, but causality is hard to establish (Friede et al., 2015; Gillan et al., 2021).
- ESG ratings disagree, so robust studies test more than one (Berg et al., 2022).
- Ethical leadership and AI auditing are active governance topics (Brown & Treviño, 2006; Laine et al., 2024).
- The credibility of sustainability claims, including carbon offsets, is a timely ethics topic (Trencher et al., 2024; Romm et al., 2025).